Executive Summary
The global M&A market in 2025 is a vibrant, multifaceted landscape, balancing opportunity with strategic caution. Deal volumes have declined 9% in H1 2025 compared to H1 2024, reflecting selective dealmaking amid economic and geopolitical complexities. However, total deal values have surged 15%, driven by a shift toward high-stakes, transformational transactions that prioritise scale, technology, and market diversification.
North America remains the global powerhouse, contributing 61% of deal value, while emerging markets like India and the Middle East are becoming growth hotspots, with deal volumes up 18% and 13%, respectively.
Strategic acquirers are reclaiming dominance, commanding 71% of global deal activity, fuelled by a resurgence in corporate confidence and a focus on AI-driven innovation.
Private equity (PE), armed with over $2.6 trillion in dry powder globally as at the end of 2024, is deploying capital with precision, targeting resilient sectors like technology, healthcare, financial and business services.
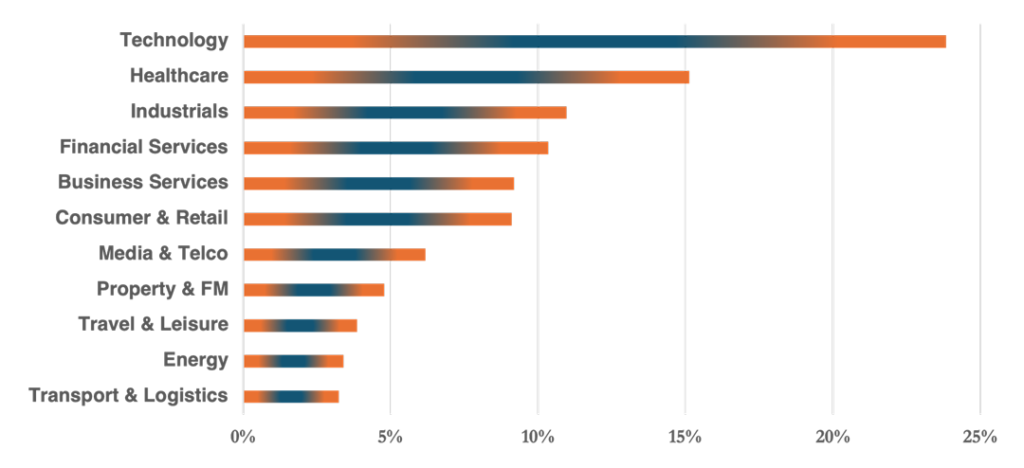
Figure 1 PE Portfolio Company Sectors – Analysis of 150 Selected PEs
The outlook for the remainder of 2025 and 2026 is cautiously optimistic, propelled by easing monetary policies, a more favourable regulatory environment, and a global push for growth. Senior executives and M&A practitioners must act decisively, leveraging technology, regional opportunities, and creative deal structures to thrive in this dynamic market.
Strategic Acquirers: Leading with Bold Vision
Resurgent Corporate Activity: After a cautious period in 2023–2024, strategic acquirers have reasserted their dominance, accounting for 71% of global deal activity in 2025, up from 61% in 2021–2022. This resurgence is driven by renewed CEO confidence, fuelled by stabilising economic conditions and clearer political landscapes in key markets. Corporates are prioritising deals that enhance competitive positioning, streamline operations, and integrate cutting-edge technologies.
Mega-Deals Drive Value: The market has seen a marked increase in transactions exceeding $1 billion and $5 billion, with technology, industrials, energy, and healthcare leading the charge. For example, a $6.2 billion acquisition of a cloud computing firm by a global tech conglomerate in Q2 2025 underscored the appetite for large-scale, tech-driven deals. These transactions aim to capture market share, integrate AI capabilities, and secure supply chains in volatile global markets.
AI and Portfolio Transformation: Strategic acquirers are aggressively pursuing both bolt-on and transformational deals to integrate next-generation technologies. AI convergence is a dominant theme, particularly in software, semiconductors, and data-driven business services. A notable example is a U.S.-based industrial giant acquiring a predictive analytics startup for $2.8 billion to enhance its smart manufacturing capabilities. These deals reflect a broader trend of portfolio simplification, where corporates divest non-core assets to fund high-growth, tech-centric acquisitions.
Regional Dynamics: North America and the UK are experiencing a robust M&A rebound, driven by political stability, declining interest rates, and strong corporate balance sheets. In contrast, Europe’s activity remains subdued due to economic uncertainty and regulatory complexities, with deal volumes down 12% in H1 2025. Asia-Pacific is mixed, with India’s vibrant deal market (up 18%) offsetting slower activity in China and Japan, where intra-regional deals dominate.
Key Article: The Strategic Imperative of Due Diligence in M&A
Key Article: Mastering Effective Operational & ESG Due Diligence in M&A
Private Equity: Precision in a Capital-Rich Environment
Record Capital Reserves: Private equity continues to wield significant influence, with global dry powder exceeding $2.6 trillion as of late 2024. Globally, PE funds hold unprecedented capital, providing substantial firepower for acquisitions and growth investments.
Growing Market Share: PE accounts for 35% of global M&A deal count in 2025 (excluding bolt-ons), a sharp rise from 23% a decade ago. This growth reflects PE’s ability to move quickly and capitalise on market dislocations, particularly in sectors with strong fundamentals.
Sector Preferences: PE firms are laser-focused on technology, healthcare, and professional services, prioritising businesses with resilient EBITDA, scalable operations, and recurring revenue streams. For instance, a $1.4 billion buyout of a telehealth platform by a mid-market PE firm in Q1 2025 highlights the sector’s appeal. Cybersecurity, cloud infrastructure, and business process outsourcing are also high-priority targets.
Exit and Valuation Challenges: Despite abundant capital, PE sponsors face hurdles in achieving premium valuations and timely exits. Average holding periods have extended to 5–7 years, prompting creative solutions like sponsor-to-sponsor deals and continuation funds. A prominent example is a $2 billion sponsor-to-sponsor transaction in the business services sector, where a PE firm sold a portfolio company to another fund to unlock liquidity.
Buy-and-Build Momentum: The buy-and-build strategy remains a cornerstone of PE dealmaking, with platform roll-ups thriving in IT, healthcare, and business services. A healthcare-focused PE fund, for example, executed three add-on acquisitions in H1 2025 to build a regional leader in outpatient care, driving operational synergies and revenue growth.
Key Article: The Private Equity Growth Formula: Navigating Complexity to Build Scalable Value
Mid-Market and Cross-Border Deals: Engines of Growth
Mid-Market Resilience: Mid-market deals ($50M–$500M) are a bright spot in the 2025 M&A landscape, offering flexibility and lower regulatory scrutiny compared to mega-deals. These transactions accounted for 45% of global deal volume in H1 2025, with strong activity in technology, healthcare, and industrials. For example, a $200 million acquisition of a niche AI software provider by a mid-sized U.S. industrial firm demonstrated the appeal of mid-market deals for scaling innovation. These transactions often enable corporates and PE firms to target high-growth, specialised assets without the complexity of larger deals.
Cross-Border Dynamics: Cross-border M&A is gaining traction, comprising 38% of global deal value in H1 2025, up from 32% in 2024. These deals are driven by the pursuit of technological expertise, market expansion, and supply chain diversification. A standout example is a $1.8 billion acquisition of a UK-based fintech firm by a U.S. financial services company, aimed at expanding digital payment capabilities in Europe. Similarly, an Indian conglomerate’s $900 million purchase of a Middle Eastern renewable energy company underscores the growing appetite for cross-border deals in emerging markets. However, cross-border transactions face challenges, including currency fluctuations, geopolitical risks, and extended regulatory reviews, particularly in jurisdictions with stringent foreign investment rules.
Strategic Implications: Mid-market and cross-border deals offer unique opportunities for agility and global reach. Corporates and PE firms are leveraging these transactions to access new markets, acquire specialised technologies, and build resilience against macro uncertainties. Success requires robust due diligence, cultural alignment, and proactive regulatory planning.
Key Article: Key Strategies to Drive Business Growth
Key Article: Driving Value Creation through Operational Transformation

Macro and Regulatory Catalysts
Monetary Policy Easing: Global central banks, including the Federal Reserve and European Central Bank, are gradually lowering interest rates, reducing borrowing costs and enhancing deal financing conditions. This shift has bolstered confidence, particularly for leveraged deals, with financing costs dropping 150 basis points in H1 2025.
Regulatory Evolution: The U.S. and UK are moving toward more deal-friendly regulatory frameworks, with streamlined antitrust processes and reduced scrutiny for mid-market transactions. However, mega-deals still face prolonged approval timelines, with 30% of $1B+ deals in 2025 delayed by regulatory reviews. In contrast, jurisdictions like China and the EU maintain stringent oversight, impacting cross-border deal timelines.
Geopolitical Stability: The resolution of election-related uncertainties in major economies, such as the U.S. and UK, has alleviated dealmaking headwinds. However, ongoing risks—trade tariffs, regional conflicts, and policy volatility—require acquirers to build flexibility into deal structures. For example, scenario planning and earn-out clauses are increasingly common in cross-border transactions to mitigate geopolitical risks.
Sector and Regional Spotlight
| Sector/Region | Key Trends |
| Technology & AI | Leading sector, with 28% of global deal value driven by AI, cloud computing, and cybersecurity. Cross-border tech deals, like a $3.5 billion U.S.-Japan semiconductor merger, are prominent. |
| Industrials | Deal values up 62% in H1 2025, fuelled by automation, supply chain resilience, and ESG-focused investments. A $1.2 billion acquisition of a robotics firm exemplifies this trend. |
| Energy | 54% YoY deal value growth, driven by renewable energy and scale. A $2.5 billion deal for a solar energy portfolio in the Middle East highlights transition priorities. |
| Healthcare | Defensive sector with consistent deal flow. A $1.6 billion PE-led buyout of a diagnostics chain underscores demand for recurring-revenue models. |
| Americas | Dominates with 61% of global deal value, led by U.S. tech and healthcare deals. A $4 billion energy sector deal in Canada reflects regional strength. |
| Europe | Deal activity down 12%, but financial services and asset management deals, like a $900 million UK-based fund acquisition, provide optimism. |
| Asia-Pacific | Subdued outside India, with intra-regional deals (e.g., a $700 million Singapore-Malaysia tech merger) driving activity. |
| India & Middle East | Outlier growth (+18% and +13% in deal volumes), with India’s tech sector and Middle East’s energy deals leading. A $1.1 billion Indian SaaS acquisition is a key example. |
Key Article: Delivering Growth in the Technology Sector
Key Article: Delivering Growth in the Healthcare & Pharmaceutical Sector
Key Article: Delivering Growth in the Energy Industry

Outlook for 2025–2026: Strategies for Winning
Cautious Optimism Prevails: As monetary and regulatory conditions normalise, M&A activity is poised to accelerate, with deal volumes projected to rise 10–12% in 2026.
Focus on Scale and Innovation: The market is trending toward fewer, larger deals that prioritise scale, AI integration, and geographic diversification. Mega-deals, like a $7 billion tech acquisition in Q3 2025, will set the tone.
Corporate-PE Collaboration: Strategic acquirers and PE firms will increasingly compete and partner, targeting high-value tech and service assets. Co-investments, such as a $2.3 billion joint venture in healthcare, are gaining traction.
Sectoral Leadership: Digital transformation, industrials, and ESG-driven deals will dominate, with healthcare and utilities providing stability amid volatility.
PE Innovation: To address exit challenges, PE firms will lean on creative structures like secondaries and sponsor-to-sponsor deals, with continuation funds projected to account for 15% of exits in 2026.
Key Article: Acquisition Integration Challenges – Navigating the Complexities
Key Article: How to Maximise Value from your M&A Advisors
Key Article: Overcoming the Challenges of Carve Outs
Actionable Insights for Executives
The 2025–2026 M&A landscape is a high-stakes arena where bold strategies, technological foresight, and global agility will define success. For senior executives and M&A practitioners, the moment to shape transformative deals is now.
- Embrace Technology: Prioritise acquisitions that integrate AI, cloud, and cybersecurity to drive innovation and market leadership.
- Target Mid-Market and Cross-Border Opportunities: Use mid-market and cross-border deals to access specialised assets and new markets with lower regulatory friction.
- Navigate Regulatory Hurdles: Invest in robust compliance and scenario planning to manage prolonged approval processes, especially for cross-border and mega-deals.
- Forge Strategic Partnerships: Collaborate with PE firms through co-investments and joint ventures to share risks and unlock high-value opportunities.
- Act with Agility: In a volatile yet opportunity-rich market, decisive, well-prepared acquirers will capture disproportionate value.
Key Article: Post-Merger Integration – A Health Check Review
Key Article: The Role of Leadership & Change Management in M&A
Sources
Sources include: Namaste Management, Goldman Sachs’ 2025 M&A Outlook, J.P. Morgan’s M&A 2025 Outlook, S&P Market Intelligence, PitchBook, BCG’s Mid-2025 M&A Insights, PwC’s Global M&A Trends 2025, Bain & Company, GS Verde Group, EY, and DLA Piper reports on M&A and PE trends (2025).